Description
STRATVECTOR DIVERSIFIED
FIVE STRATEGIES. FIVE MARKETS. ONE SYSTEMATIC PORTFOLIO.
StratVector Diversified is a multi-strategy cBot for cTrader that combines five independent systematic trading modules across Bitcoin, DOT, Ethereum, Gold and XRP.
Instead of relying on a single market or trading approach, Diversified spreads trading opportunities across several independent strategy modules, market behaviours and timeframes.
The goal is simple:
Broader diversification inside one automated trading system — combined with equity-based position sizing and portfolio-level risk control.
WHY DIVERSIFIED?
Diversified is designed for traders who want exposure to several different markets without running multiple separate bots.
The portfolio combines:
- Bitcoin — Long
- DOT — Short
- Ethereum — Long
- Gold — Long
- XRP — Short
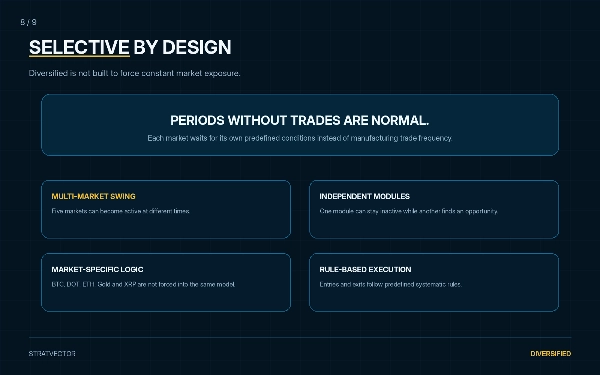
Each module operates independently and only trades when its own predefined conditions are met.
This means the portfolio does not need every market to perform at the same time.
Some modules may remain inactive for extended periods while others generate trading opportunities.
FIVE INDEPENDENT STRATEGY MODULES
Bitcoin
Systematic long strategy operating on Bitcoin.
DOT
Systematic short strategy operating on DOT.
Ethereum
Systematic long strategy operating on Ethereum.
Gold
Systematic long strategy using Gold together with additional Silver market data as a reference input.
XRP
Systematic short strategy with dynamic trade-management logic.
Each module uses its own predefined entry, exit and trade-management rules.
Proprietary signal thresholds and internal strategy logic are embedded inside the cBot and are not exposed as user-configurable strategy parameters.
TRADED MARKETS
Actively traded:
Bitcoin
DOT
Ethereum
Gold
XRP
Silver / XAG is reference data only.
Diversified does not open Silver positions.
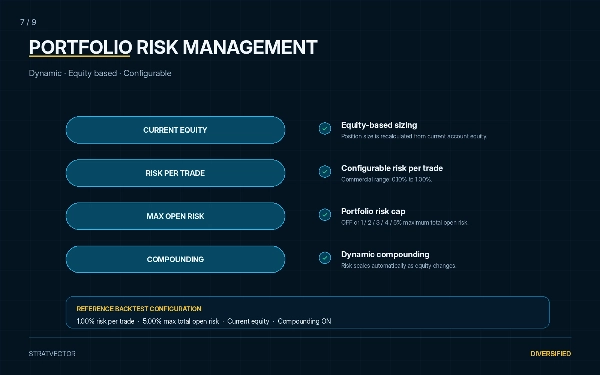
PORTFOLIO RISK MANAGEMENT
Diversified uses a central portfolio-level risk engine.
Risk per Trade
Configurable from:
Default:
Maximum Total Open Risk
Available settings:
OFF · 1% · 2% · 3% · 4% · 5%
Default:
Position sizing is calculated dynamically from the current account equity.
As equity changes, position sizing adjusts automatically.
The portfolio risk engine also monitors the combined planned risk of open positions and can block additional entries when the configured maximum total open risk would be exceeded.
Dynamic Compounding
Enabled.
Risk sizing scales automatically with current account equity.
AUTOMATED PORTFOLIO EXECUTION
Once configured, StratVector Diversified automatically handles:
- signal evaluation
- position sizing
- portfolio risk checks
- trade entry
- stop management
- trade exits
- strategy-specific trade management
The system is designed to run as a systematic portfolio, not as a high-frequency trading bot.
Periods with fewer trades — or no trades at all — are normal when valid setups are absent.
RECOMMENDED STARTING CAPITAL
$5,000 or more is recommended.
Diversified uses percentage-based equity sizing, but broker minimum trade sizes and volume increments can reduce sizing precision on very small accounts.
A starting balance of $5,000 or more provides better position-sizing granularity across the different markets.
Smaller balances may technically work but can be more affected by broker minimum-volume restrictions.
DEFAULT SYMBOL MAPPING
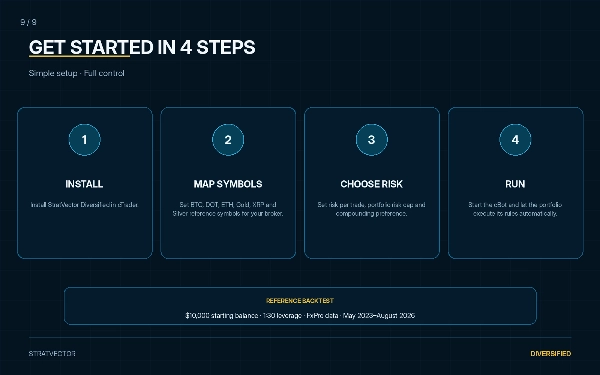
Reference configuration used with FxPro:
BTC: BITCOIN
DOT: POLKADOT
Ethereum: ETHEREUM
Gold: XAUUSD
XRP: XRP
Silver reference: XAGUSD
Broker symbol names can differ.
All market mappings can therefore be adjusted through the public cBot parameters.
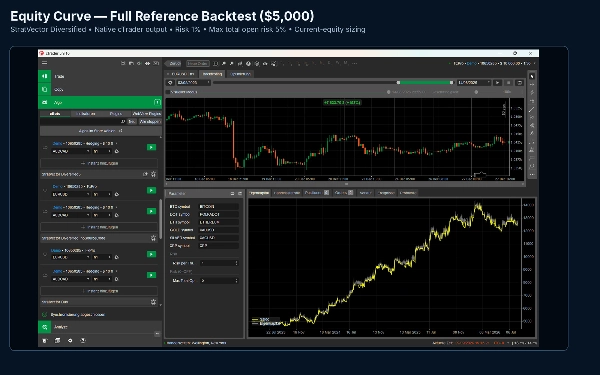
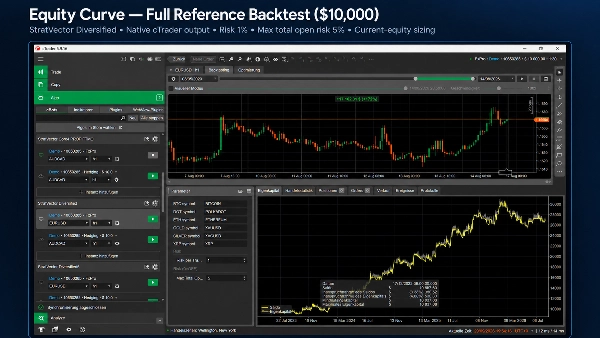
The current reference backtest used exactly these mappings together with 1.00% risk per trade and 5.00% maximum total open risk.
REFERENCE BACKTEST
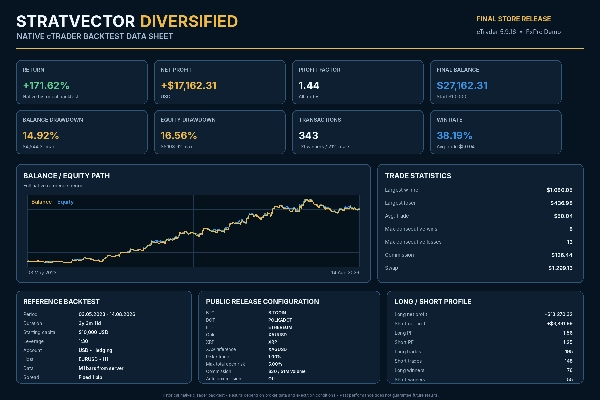
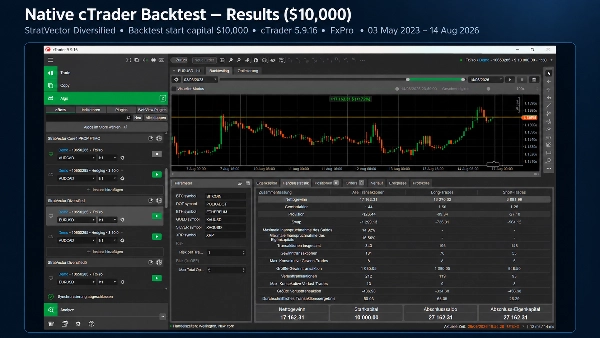
Starting balance: $10,000
Final balance: $27,162.31
Net profit: +$17,162.31
Return: +171.62%
Profit factor: 1.44
Total trades: 343
Winning trades: 131
Losing trades: 212
Max. balance drawdown: 14.92%
Max. equity drawdown: 16.56%
Long trades: 195
Short trades: 148
The native cTrader report confirms 343 closed trades, including 131 winners and 212 losers.
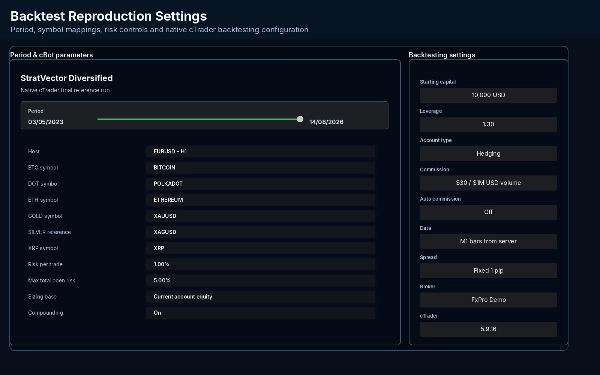
Backtest Configuration
Platform: cTrader Desktop
Broker: FxPro Demo
Account: USD · Hedging
Starting balance: $10,000
Leverage: 1:30
Period: 03 May 2023 – 14 August 2026
Host: EURUSD · H1
Historical data: M1 bars from server
Spread: Fixed 1 pip
Commission: $30 per $1 million USD volume
Risk per trade: 1.00%
Max total open risk: 5.00%
The native report confirms the $10,000 starting balance, $27,162.31 ending balance, +171.62% return and the full test period.
ADDITIONAL $5,000 CAPITAL TEST
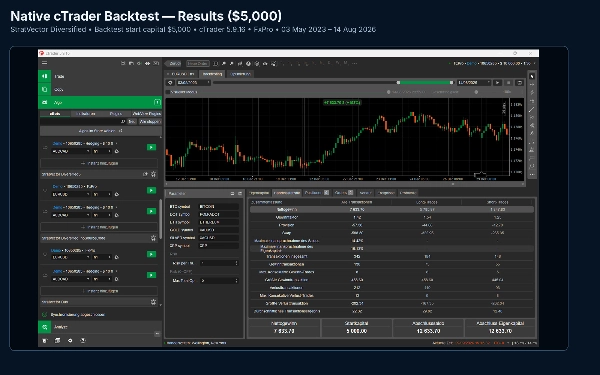
A second native cTrader backtest was performed using the same strategy configuration and reference period with a reduced starting balance of $5,000.
Starting balance: $5,000
Return: +152.67%
Net profit: +$7,633.70
Final balance: $12,633.70
Profit factor: 1.42
Max. balance drawdown: 14.42%
Max. equity drawdown: 16.13%
Trades: 342
This additional test is included to document position-sizing behaviour around the recommended starting-capital level.
WHAT DIVERSIFIED IS NOT
StratVector Diversified is not designed to force constant market exposure.
It is not built around:
- constant trading activity
- unlimited portfolio exposure
- manually selected trades
- identical logic across every market
Each strategy module waits for its own predefined conditions.
That selectivity is an intentional part of the system.
IMPORTANT INFORMATION
Correct broker symbol mapping is required.
Symbol names, contract specifications, minimum trade sizes, volume increments, spreads, commissions, swaps and execution conditions can vary between brokers.
Historical backtests depend on the specific broker data and trading conditions used during testing.
Live trading results can differ materially from historical backtest results.
Trading involves risk. Past performance does not guarantee future results.
COMPATIBILITY
Verified on cTrader Desktop 5.10.16.
No strategy or risk-model changes were required for cTrader 5.10.16 compatibility.
Summary
The system employs a multi-market, multi-timeframe architecture with equity-based dynamic position sizing and compounding. Portfolio-level risk controls include configurable risk per trade (default 1%) and maximum total open risk (default 5%), with automatic trade and position management to maintain risk limits. The cBot supports long and short strategies, applying centralized risk management that can reject new entries if risk thresholds are exceeded.
Recommended starting capital is $5,000 or more to ensure adequate position-sizing granularity given typical broker constraints. Backtests on cTrader with FxPro data (1:30 leverage, May 2023–August 2026) show returns above 150% with maximum drawdowns around 15%, a profit factor near 1.4, and over 340 trades executed.
Broker symbol mappings are adjustable to accommodate different naming conventions and contract specifications. The system operates with market orders on hourly charts and uses indicators such as ADX, Keltner Channels, and Donchian Channels within its trend-following, low-frequency swing trading approach.